
Public Sector Banks in India: List, Financial Performance, Role and Importance for Economic Growth
Public sector banks remain an important part of India’s financial system. They accept deposits, provide loans, support businesses and households, facilitate government-linked banking services...

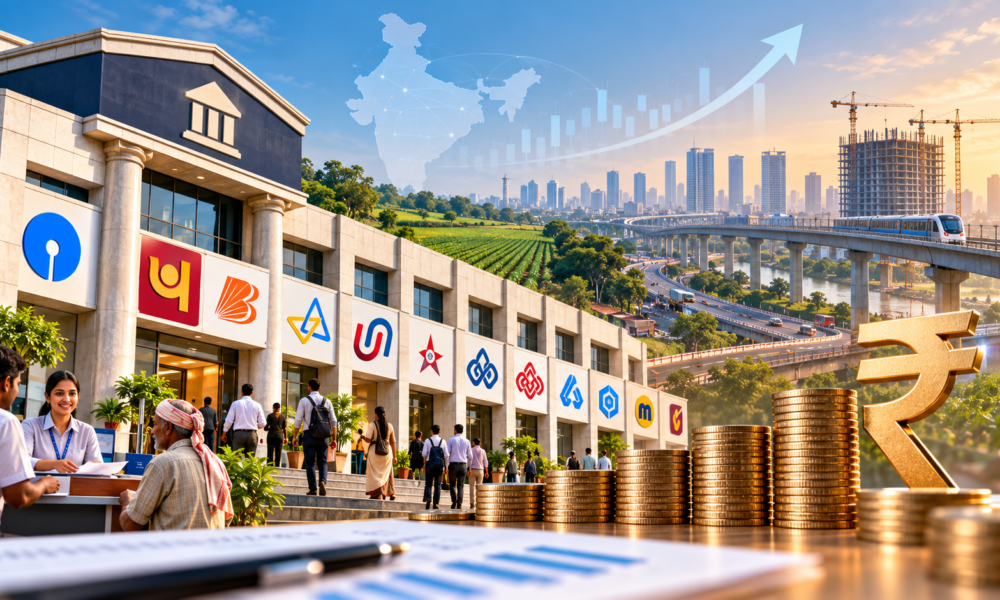
Public sector banks remain an important part of India’s financial system. They accept deposits, provide loans, support businesses and households, facilitate government-linked banking services and channel savings into economic activity.
Their role extends beyond everyday banking. Infrastructure projects, small businesses, agriculture, housing and industrial development all depend on access to credit.
According to the Press Information Bureau, India’s public sector banks recorded a combined net profit of ₹1.98 lakh crore in financial year 2025-26, their fourth consecutive year of aggregate profitability.
What Are Public Sector Banks?
Public sector banks are banks in which the government holds a majority ownership stake, subject to the applicable legal framework.
They operate under the supervision of the Reserve Bank of India and provide savings accounts, fixed deposits, personal loans, business loans, agricultural credit, payments and digital banking services.
Their extensive branch networks also help connect customers in smaller cities and rural areas with formal financial services.
List of Public Sector Banks in India
The Department of Financial Services lists 12 public sector banks in India.
- State Bank of India
- Punjab National Bank
- Bank of Baroda
- Canara Bank
- Union Bank of India
- Bank of India
- Indian Bank
- Central Bank of India
- Indian Overseas Bank
- UCO Bank
- Bank of Maharashtra
- Punjab & Sind Bank
Financial Performance in FY 2025-26
Government-reported aggregate figures indicate stronger financial performance across the public sector banking system.
- Combined net profit: ₹1.98 lakh crore
- Total business: ₹283.3 lakh crore as of 31 March 2026
- Gross NPA ratio: 1.93% as of 31 March 2026
- Year-on-year business growth: 12.8%
These figures indicate growth in banking activity alongside an improvement in asset quality. However, aggregate performance does not mean every bank has the same profitability, risk exposure or capital position.
Investors should examine individual bank results, capital adequacy, loan growth, deposit costs and asset quality before drawing conclusions about a particular institution.
What Are Non-Performing Assets?
Non-performing assets (NPAs) are loans for which repayments have remained overdue beyond the applicable regulatory threshold, generally 90 days for conventional term loans.
The gross NPA ratio measures stressed loans relative to gross advances. A lower ratio can indicate improved recovery, stronger credit underwriting or fewer fresh defaults.
The government reported a gross NPA ratio of 1.93% and a net NPA ratio of 0.39% for public sector banks as of 31 March 2026. It also reported provisioning coverage above 90% for each public sector bank.
These indicators should be considered alongside loan growth, write-offs, recoveries and the risk profile of new lending.
How Do Public Sector Banks Support Infrastructure?
Infrastructure development requires substantial long-term capital. Roads, renewable energy installations, industrial parks, logistics facilities, housing developments and power projects may require financing over extended periods.
Public sector banks can support these activities in several ways.
Project Finance
Banks may provide loans to eligible infrastructure projects after evaluating financial viability, regulatory approvals, cash flows and risks.
Working Capital
Construction companies, equipment suppliers and contractors need funds to purchase materials, pay workers and meet operating expenses.
MSME Finance
Small and medium-sized businesses supply building materials, electrical equipment, transport services and specialist labour to infrastructure projects.
Housing Finance
Housing loans help households purchase homes and support activity across construction and related industries.
Not every infrastructure project receives direct lending from public sector banks. Financing arrangements vary according to the project, borrower, risk allocation and involvement of other lenders.
Digital Banking and Financial Inclusion
Digital payments, mobile banking, internet banking and automated services have changed how customers access financial services.
Digital transformation can improve convenience and expand access to customers who cannot frequently visit a physical branch.
However, digital banking also creates responsibilities around cybersecurity, fraud prevention and customer awareness.
Financial inclusion involves more than opening accounts. Customers need reliable access to payments, suitable savings products, responsible lending and clear information about fees.
Risks and Challenges Facing Public Sector Banks
Public sector banks must continue managing credit risk, interest-rate changes, technology investment and competition from private lenders.
For infrastructure lending, delays in land acquisition, regulatory approvals, construction and project revenues can affect repayment schedules. Careful due diligence and ongoing monitoring are therefore essential.
Conclusion
Public sector banks are a significant pillar of India’s financial infrastructure. Their role includes supporting households, businesses, agriculture, financial inclusion and eligible infrastructure projects.
The ₹1.98 lakh crore combined net profit reported for FY 2025-26 points to a stronger sector. The next challenge is to maintain that resilience while expanding credit responsibly, investing in technology and financing productive economic activity.




No Comment! Be the first one.